Understanding smsf loan interest rates helps trustees budget for property inside their fund without unpleasant surprises part way through.
SMSF loans sit above standard home loan rates, and they carry establishment costs of their own that catch trustees out if they only compare the headline rate.
The rate is genuinely only part of the picture, and often not the most important part for a smaller fund.
This guide explains smsf loan interest rates, what drives them, and the other costs to plan for. This guide is general information only, not personal financial advice. SMSF borrowing is complex and strictly regulated, so confirm your plan with a licensed financial adviser and your accountant.
Under a limited recourse arrangement, the lender’s claim is confined to the single property. They cannot pursue the fund’s other assets if things go wrong.
That restriction increases their risk, and smsf loan interest rates reflect it directly.
It is a structural feature of the product rather than a comment on your fund’s quality.
Pricing varies by whether the property is residential or commercial, with commercial generally priced higher and requiring a larger deposit.
The fund’s balance and contribution history also feed into the assessment.
A stronger fund with a larger deposit will usually be offered better terms.
A larger deposit reduces the loan to value ratio and usually earns a sharper rate, just as it does on a standard loan.
A fund with a healthy balance and consistent contributions presents as lower risk, and lenders price that accordingly.
Because relatively few lenders offer this product, we compare the whole available panel through our SMSF loan broker Perth service.
Category :
Share :
After 10 years inside the Big Four banks, I saw how many Perth families missed out or borrowed with the wrong lender. The Finance Yogi exists to change that - we compare the whole market and explain every number in plain English.
Mohit Brahmbhatt
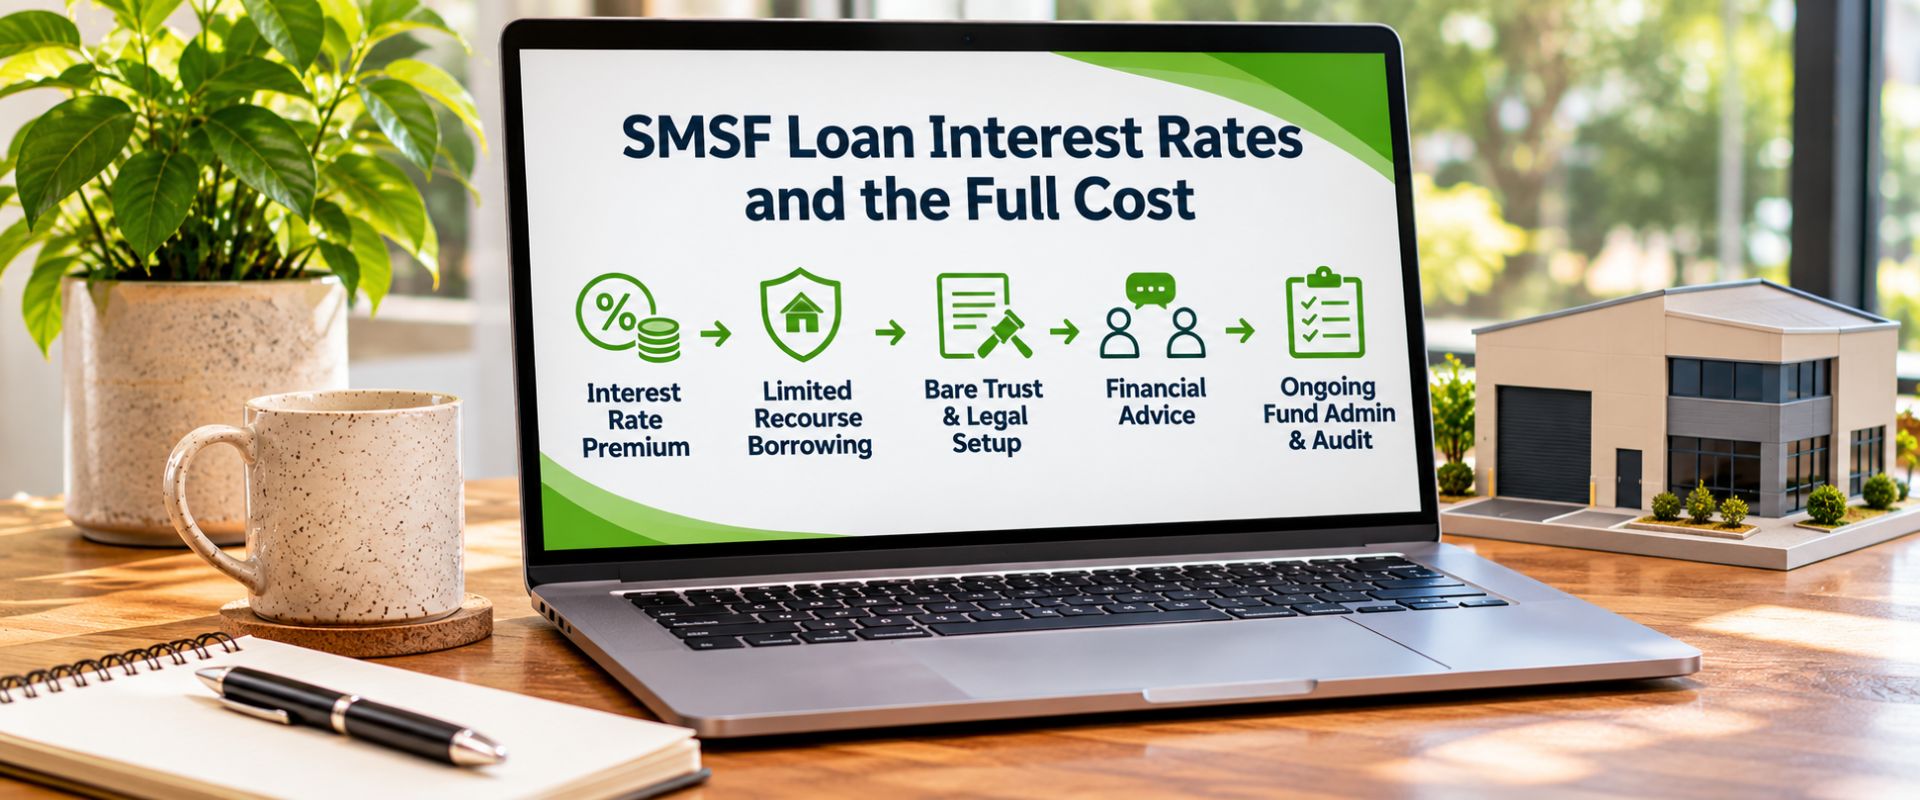
Establishing the bare trust carries a legal cost, and it must be done correctly because errors here are expensive to remedy later.
Licensed financial advice is effectively mandatory for this strategy, and that advice carries a fee of its own.
Lender establishment fees on SMSF loans are typically higher than on standard home loans, reflecting the additional complexity.
Ongoing fund administration and audit costs also rise once the fund holds a geared property.
Add every one of those costs together before deciding whether the strategy stacks up, because the rate alone understates the real figure.
Our guide to SMSF property investment in Perth covers the fund requirements behind these costs.
Smsf loan interest rates and fees vary widely between the lenders that offer this specialised finance, more so than on standard lending.
On a long term loan, even a small difference in rate compounds into a meaningful sum over the life of the facility.
Fewer lenders in the market means less competitive pressure, which makes active comparison more valuable rather than less.
Policy differences matter just as much as price, since one lender may decline a property another is comfortable with.
Compare establishment fees, ongoing fees and the rate together, and weigh the lender’s policy on your specific property type.
For commercial premises, see our guide to the SMSF commercial property loan.
Before committing, price out every item below.
Together they give you the real cost of the strategy rather than the advertised one.
If the numbers are marginal once everything is counted, that is worth knowing early.
With the full picture, smsf loan interest rates can be weighed properly against the strategy’s benefits.
We compare the panel and set out the total cost in writing. Explore our finance services.
Book a free, no-obligation chat and we will set out the full cost, not just the rate.
Source: SMSF guidance from the ATO on self-managed super funds, and super information from ASIC MoneySmart on SMSFs. SMSF rules are complex, so seek licensed financial advice before acting.