SMSF Borrowing Checklist
Before your self-managed super fund can borrow to buy property, it needs to meet a set of strict requirements. This free checklist covers the boxes to tick before an LRBA.
Before your self-managed super fund can borrow to buy property, it needs to meet a set of strict requirements. This free checklist covers the boxes to tick before an LRBA.
Before you refinance, a quick readiness check tells you whether switching will actually save you money. This free checklist covers the documents, equity and rate checks to run first.
Being self-employed does not have to make your home loan harder – it just needs the right documents. This free checklist covers everything lenders ask business owners for in WA.
Before you buy an investment property, running the real numbers tells you whether it will add to your wealth or drain your cash. This free checklist covers every figure to check first.
Getting your documents ready is the fastest way to a smooth first home purchase. This free checklist covers everything you need for pre-approval, the First Home Owner Grant and settlement in WA.

Self-employed home loan requirements have eased in 2026. All four major banks now accept just one year of financials, so you no longer always need two years of tax returns to buy.
An SMSF property loan usually needs a larger deposit than a standard loan – typically 20% to 30% – plus a cash buffer and a fund balance that lenders consider sufficient.
Choosing between a chattel mortgage, lease and hire purchase can save or cost your business real money. This free checklist compares them on the points that matter.
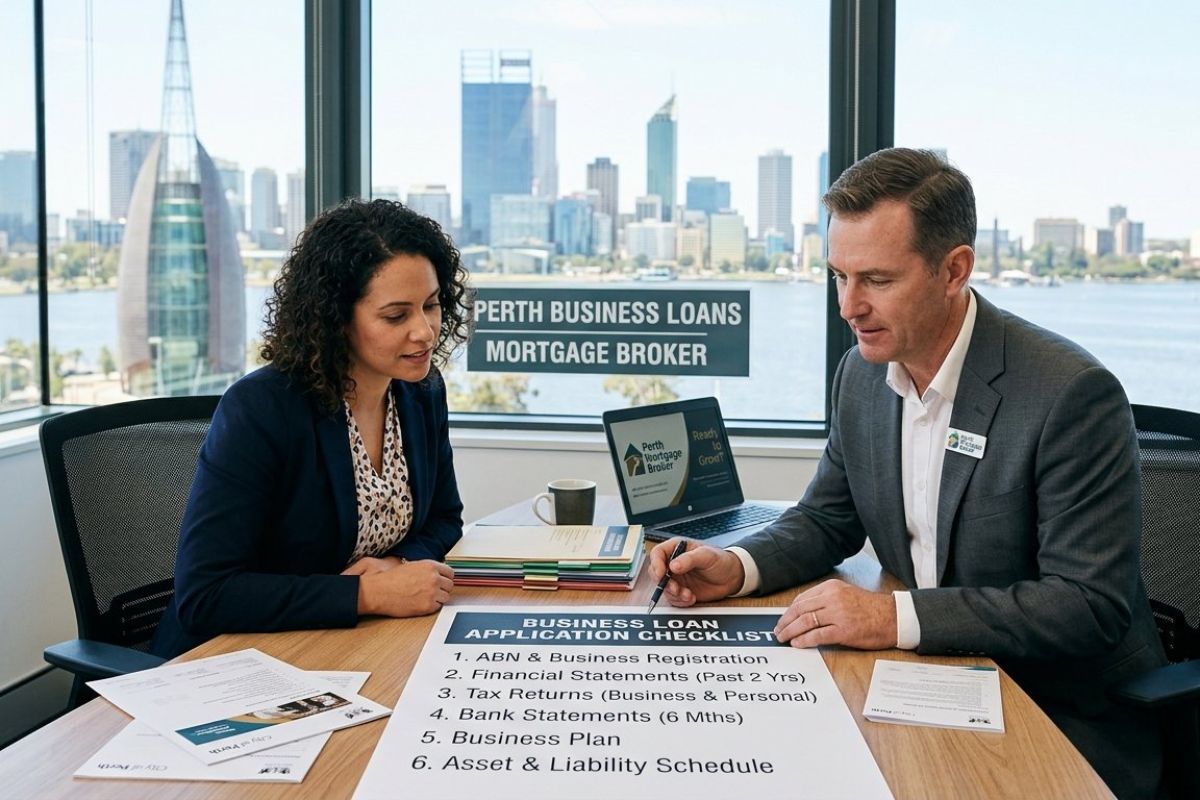
A well-prepared application is often the difference between a business loan approval and a decline. This free checklist covers the financials and documents lenders want to see.
An offset account and a redraw facility both reduce the interest you pay on your home loan, but they work differently – and for investors, the difference matters for tax.
Building a home runs smoothly when your finance keeps pace with the build. This free checklist covers the contract, plans, permits and documents you need for each drawdown stage.
Buying property through a self-managed super fund can be a powerful way to invest for retirement – but it is strictly regulated, and getting the structure right is essential.
Refinancing means moving your home loan to a better deal – usually a lower rate, but also to unlock equity or consolidate debt. With rates at a 15-year high in 2026, it is more worthwhile than ever.
Keystart is a Western Australian Government lender that helps buyers into a home with as little as a 2% deposit and no Lenders Mortgage Insurance.
Being self-employed should not stop you buying a home – and in 2026 it is easier than ever, with all four major banks now accepting just one year of financials.
Having the right documents ready is the simplest way to a fast home loan approval. This free checklist covers the ID, income, savings and expense paperwork lenders ask for in Perth.
A good mortgage broker can save you time, stress and thousands of dollars – but not all brokers are equal. Knowing what to look for helps you choose the right one.
A low-doc home loan lets self-employed borrowers prove their income with alternatives to full tax returns – such as BAS, bank statements or an accountant’s letter.
Financing an investment property well is about more than getting a loan – it is about structure, cash flow, borrowing power and tax, all working together.
Getting approved for a business loan comes down to four things: your trading history, your cash flow, the security you can offer, and how well your application is presented.
Getting a home loan in Perth is simpler when you understand the journey – from working out your deposit and borrowing power to comparing lenders and settling.
Equipment finance lets your business buy the vehicles, machinery and gear it needs without draining cash – spreading the cost over the asset’s working life instead.
Buying your first home in Western Australia is exciting – and far simpler once you understand the grants, deposits and steps involved.
Refinancing means replacing your current home loan with a new one – usually to get a lower rate, unlock equity, or consolidate debt.
Building a home in WA is exciting, and a construction loan is the finance that makes it happen – releasing funds in stages as your builder progresses.

How much you can borrow for a home loan in Perth depends on your income, living expenses, existing debts and a mandatory stress test set by the regulator, APRA.
Whether you are buying a car or funding a big purchase, the right loan can save you thousands – and the wrong one, usually dealer finance, can quietly cost you.
The right business finance can fuel growth; the wrong structure can strain your cash flow. Understanding your options is the first step to borrowing well.
A construction loan is a home loan that releases funds in stages as your builder completes each phase of the build, rather than all at once.
Equipment finance lets your business buy the vehicles, machinery and gear it needs without paying the full cost upfront, spreading it over the asset’s working life instead.