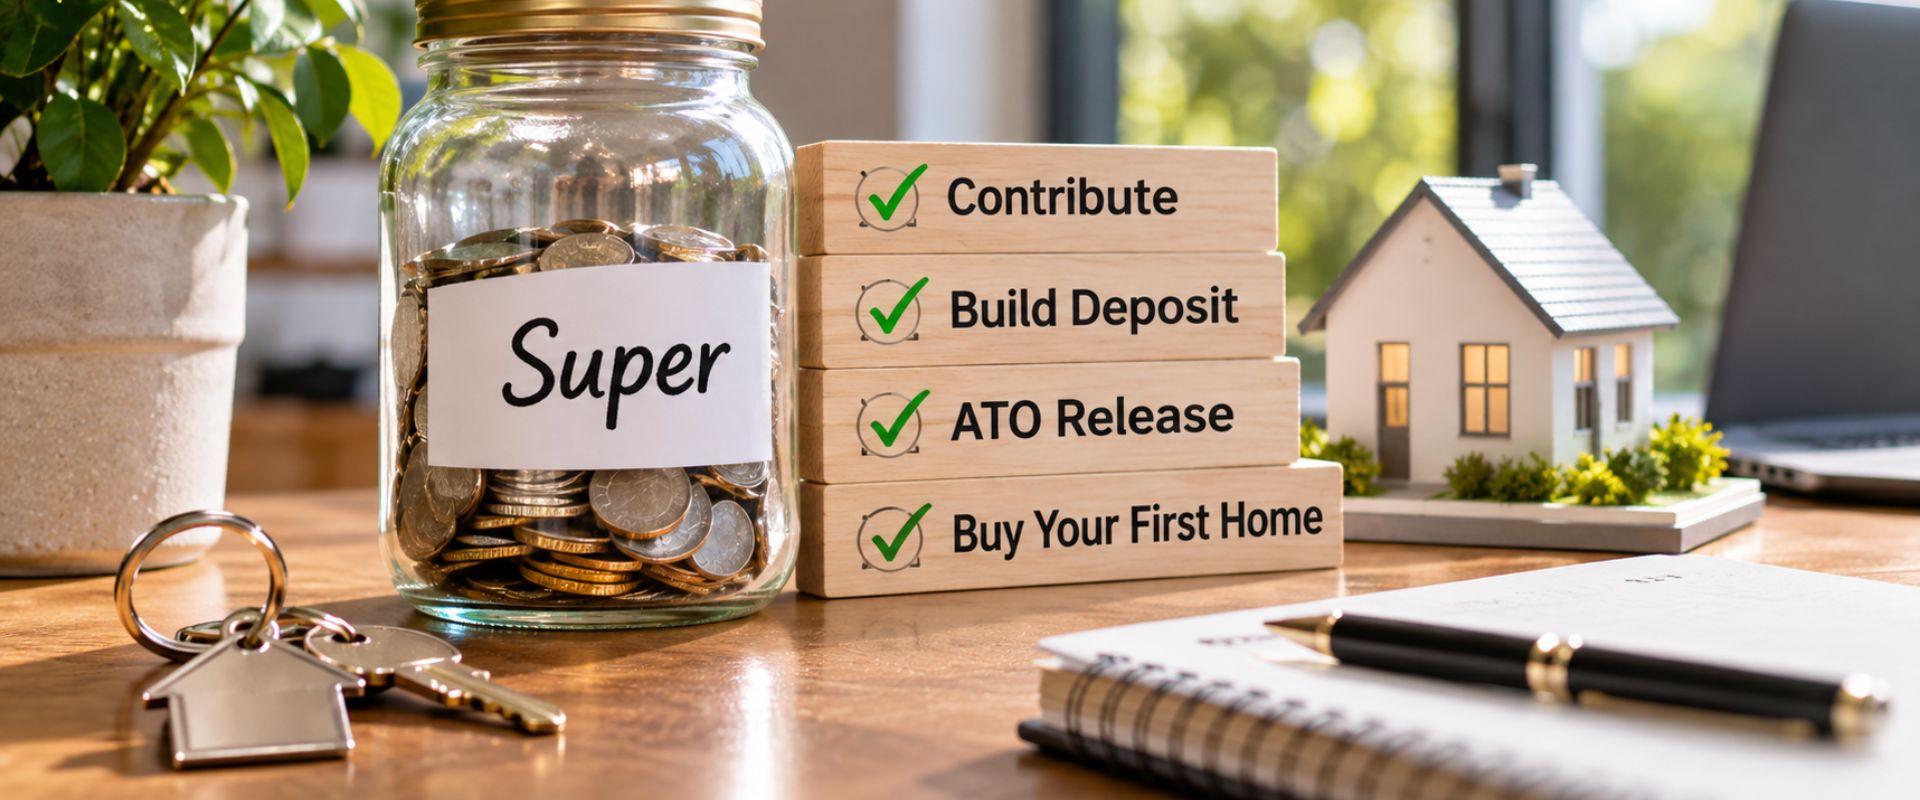
The first home super saver scheme lets you save part of your home deposit inside superannuation, where it is taxed more lightly than ordinary savings.
For many Perth buyers that concessional treatment means the deposit grows faster than it would in a standard savings account.
It is one of the few genuine advantages available to first home buyers, and yet a surprising number never use it.
This guide explains how the first home super saver scheme works. The caps and rules change, so confirm the current detail with the ATO or an adviser.
Concessional contributions are generally taxed at a lower rate than your marginal income tax rate, so more of each dollar survives to become deposit.
That difference compounds over two or three years of disciplined saving.
The first home super saver scheme simply gives you a way to access those savings for a first home, which super normally would not allow.
The money is held in your super fund and earns a deemed rate of return until you withdraw it.
Because it sits inside super, it is also harder to dip into for everyday spending, which many savers find genuinely useful.
That enforced discipline is an underrated part of the benefit.
Contributions can be made through salary sacrifice or as personal after tax contributions, and the tax treatment differs between the two.
Only voluntary contributions count. Your employer’s compulsory contributions are not accessible under the scheme.
We fit the scheme into the wider deposit plan through our first home buyer mortgage broker Perth service.
After 10 years inside the Big Four banks, I saw how many Perth families missed out or borrowed with the wrong lender. The Finance Yogi exists to change that - we compare the whole market and explain every number in plain English.
Mohit Brahmbhatt
When you are ready to buy, you apply to the ATO for a release determination before signing a contract, not after.
The ATO calculates how much you can withdraw, including associated earnings, and tax is applied to the released amount at a concessional rate.
Release takes time to process, so starting the application well before you intend to make an offer avoids a settlement scramble.
Once released, you generally have a set period in which to purchase, and there are consequences if you do not.
Speak to your broker and the ATO about timing before you start seriously house hunting, because the sequence matters.
Model what the released amount does to your position with our borrowing power calculator.
The first home super saver scheme is not an alternative to other help. It sits alongside low deposit lending and state based assistance.
A buyer might use released super as part of the deposit while also accessing a low deposit loan for the balance.
That combination can bring forward a purchase by years compared with saving conventionally.
Your eligibility for each form of support is assessed separately, so being outside one does not rule out the others.
Map every source of deposit together, including savings, released super, and any family assistance, before setting a purchase timeline.
See the lending options in our guide to buying with a low deposit in WA.
Confirm each point below before relying on the scheme in your deposit plan.
The caps and timing rules are where most problems arise.
A short conversation with your adviser resolves nearly all of them.
With those confirmed, the first home super saver scheme becomes a reliable part of your deposit rather than a guess.
We build it into the overall plan. Explore our finance services or our Keystart eligibility guide.
Book a free, no-obligation chat and we will map every source of deposit available to you.
Source: scheme guidance from the ATO on the First Home Super Saver Scheme, and savings information from ASIC MoneySmart on first home savings. Caps and rules change, so confirm the current detail before you act.